Mid-term election drama has gold and silver sharply higher, while oil, bond yields, and the dollar ease.
There are reasons to believe that the potential for gold and silver prices to move higher could be explosive. The background is one of severe mispricing due to war propaganda, continual draining of physical metal from Western capital markets, and subdued speculator interest. Could it be that these distortions are finally being uncovered by the dramatic success of the Democrats in the midterms?
It was apparent that the surprise success of the Democrats in capturing both houses from Republican control was the signal for a significant bear squeeze on the shorts in gold and silver. The chart below illustrates how over the last five months gold’s open interest on Comex has gradually recovered from ultra-low levels to be simply oversold at 400,000 contracts.
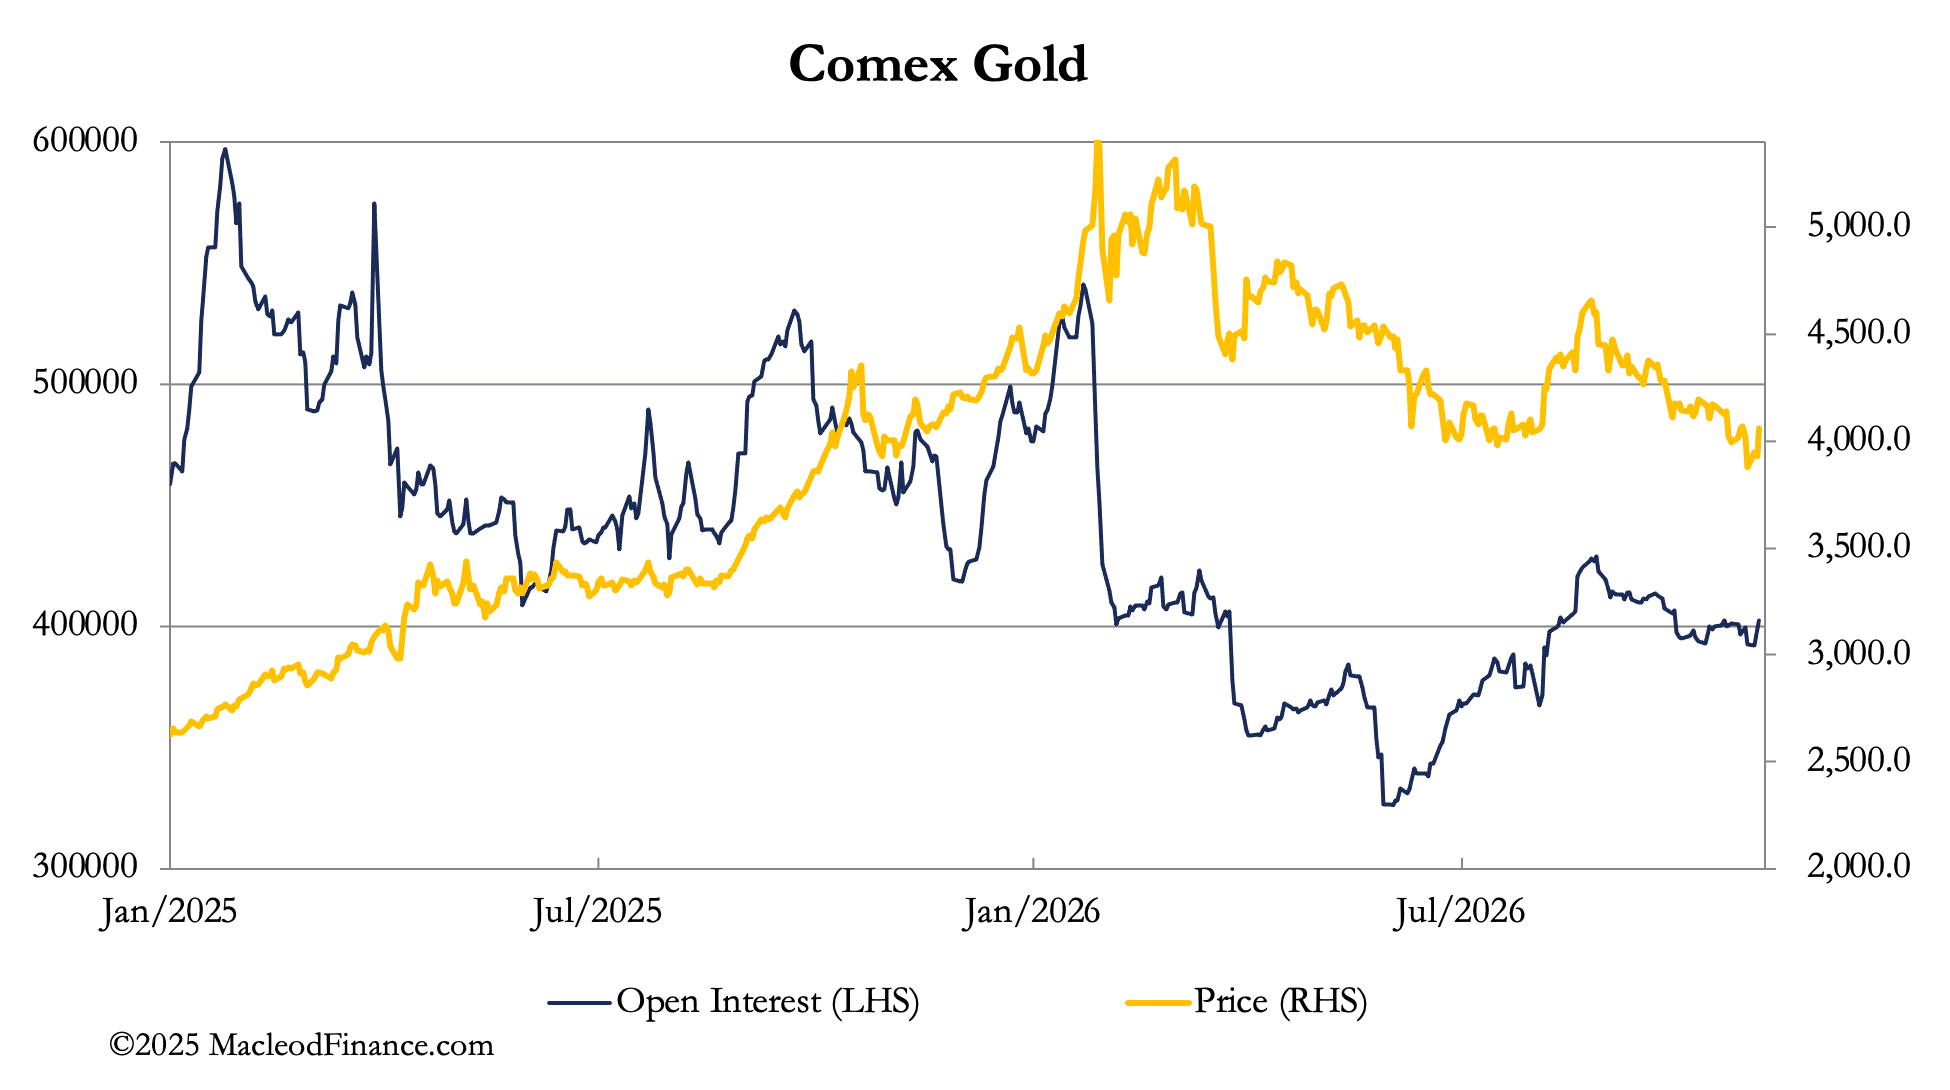
It reflects some accumulation at low prices, but there is evidence that the paper market is being sidelined. Customs data confirms that China imported 1,220 tonnes this year to August including monetary gold, and the last two months will have added significantly to that total. If Comex has a contribution to the physical market, its stand for delivery system has delivered 621 tonnes into buyers’ hands so far this year. Buyers are big and are mostly going directly to the refiners, so paper derivatives reflect price hedging activity against off-market deliveries rather than genuine supply and demand factors.
Rather than follow paper market developments, investors would do better to follow factors likely to change the dollar’s purchasing power, which means cutting through propaganda seemingly designed to support it and financial markets. There have been widespread claims in the US media that oil flows through Hormuz are almost back to normal at up to 16 million barrels a day. However, IMF analysis suggests otherwise:
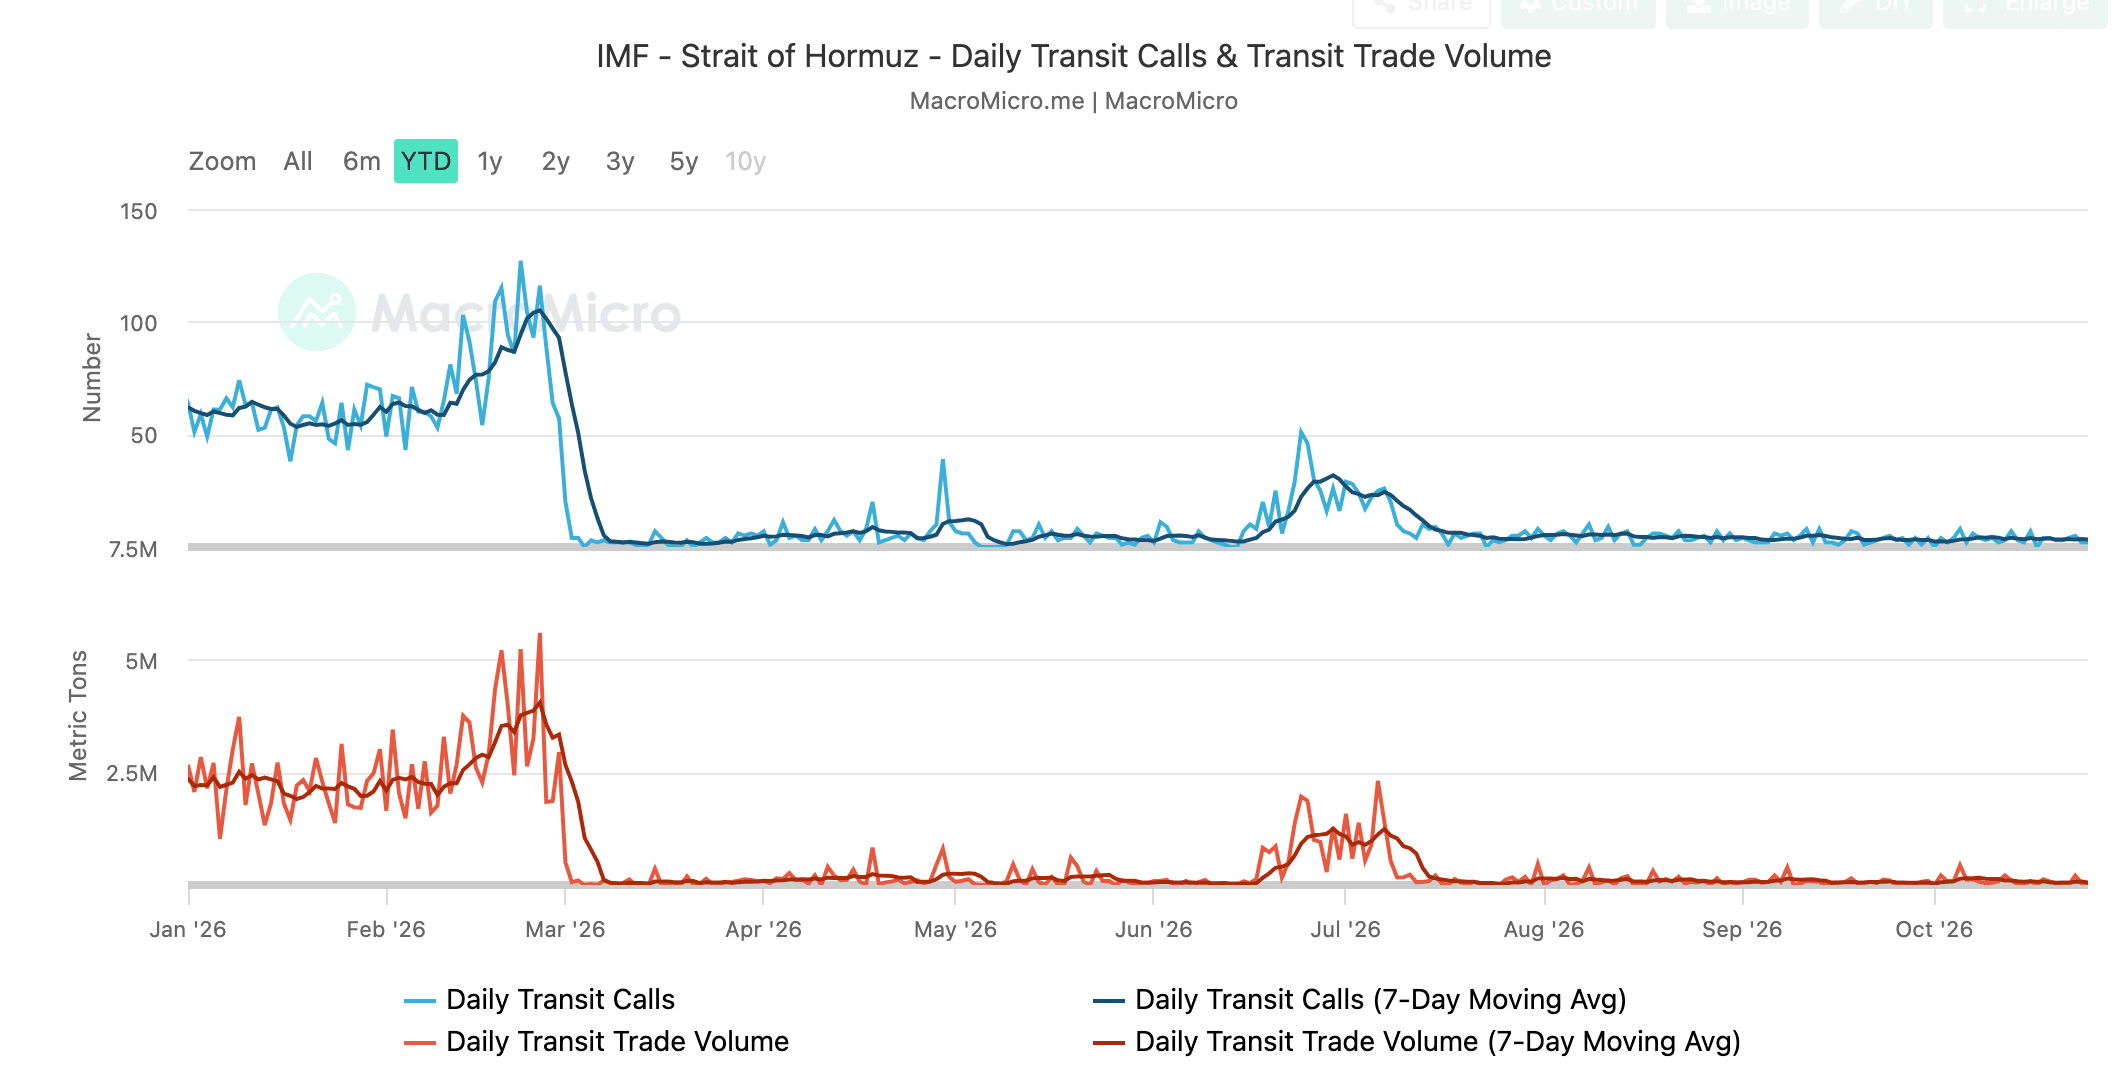
According to the IMF’s tracking data, only 3 ships on average over the seven days to 25th October went through the Strait, with only 2 ships on this date. Some oil, up to 2mbpd is reportedly pumped from the UAE overland, but Houthi activity is believed to have effectively closed the Saudi pipeline to Yanbu removing up to 6mbpd otherwise assumed to be flowing.
There is little doubt that financial markets have been thoroughly misled over the true quantity of oil emanating from the Middle East and that there’s an information shock to come. Meanwhile, the credit bubble in equity markets is already beginning to deflate, with AI and semiconductor stocks falling sharply yesterdday. The chart below shows hourly movements in the S&P500 Index:
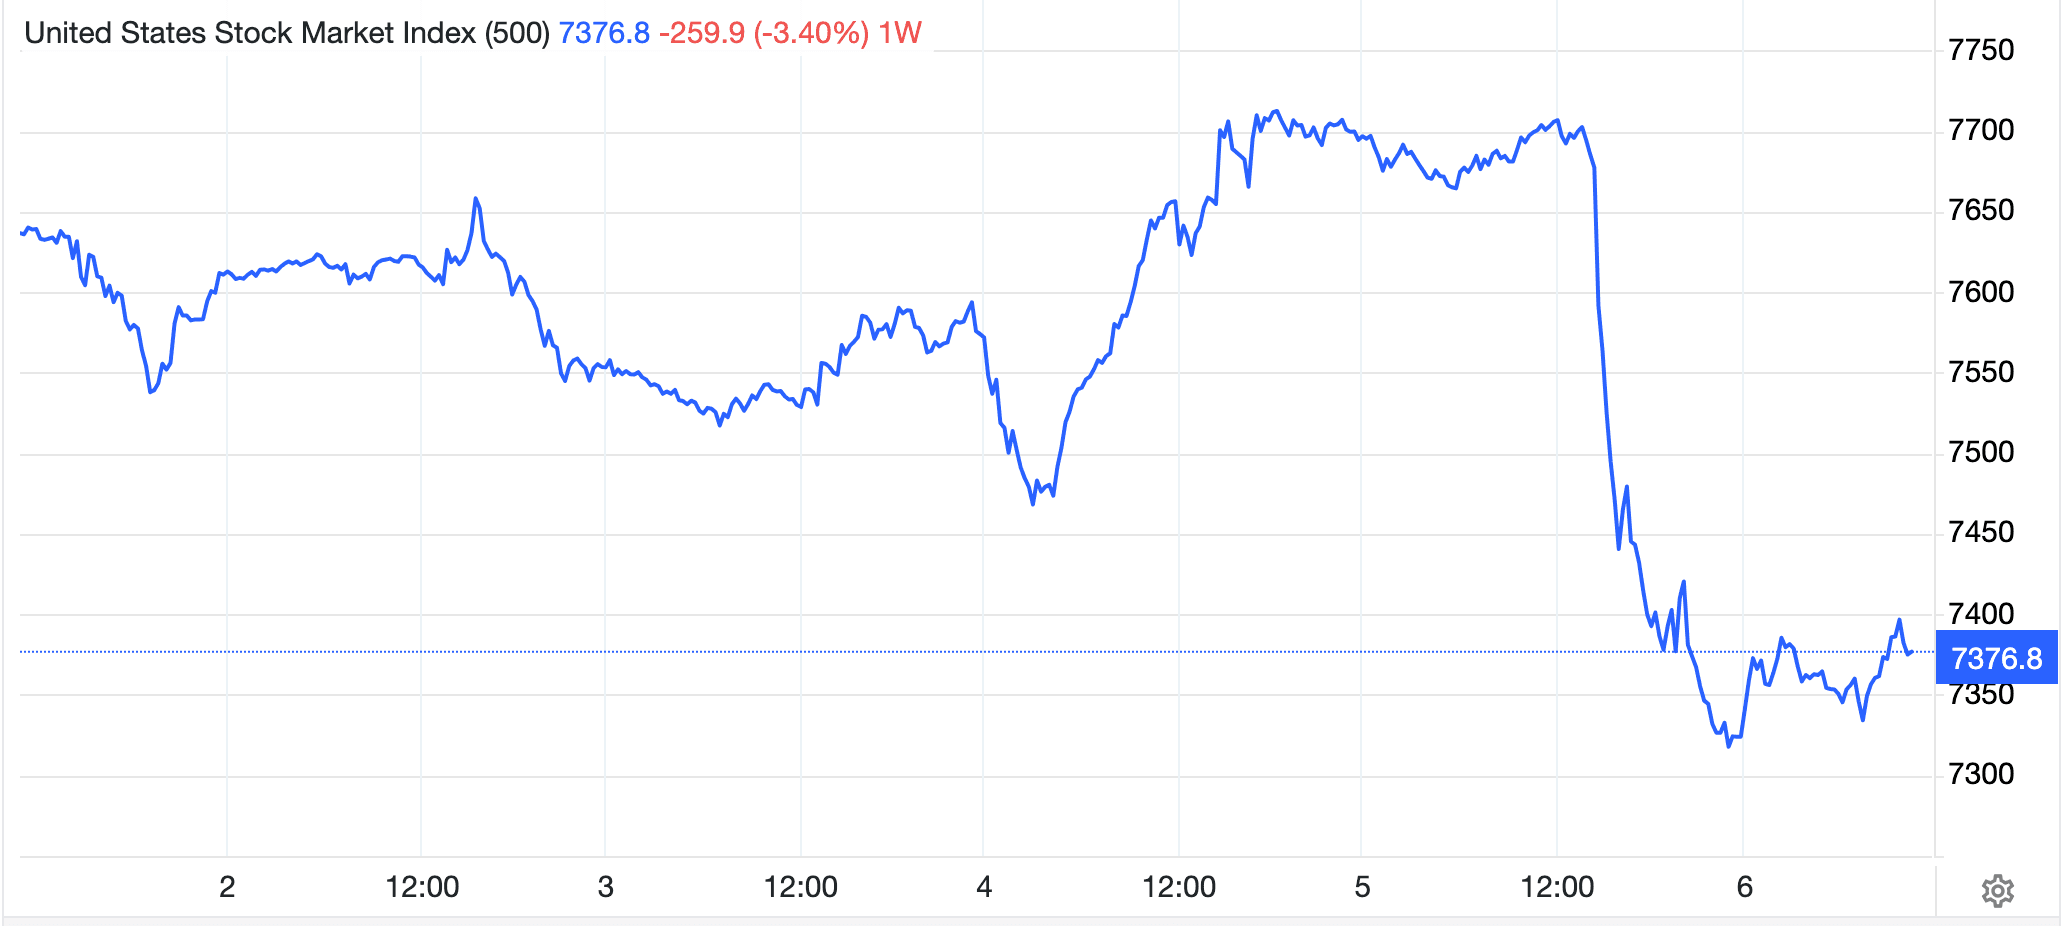
Is this the start of a wider financial unravelling? Investors will hope not. But there is a general instability in financial markets becoming exposed, even before the truth over oil supplies from the Persian Gulf is revealed to markets.
Put another way, risk in credit is increasing, whether it be from disinformation or the unwinding of excessive credit. And having removed its own speculator class, China has bought up the physical gold available without driving prices higher.
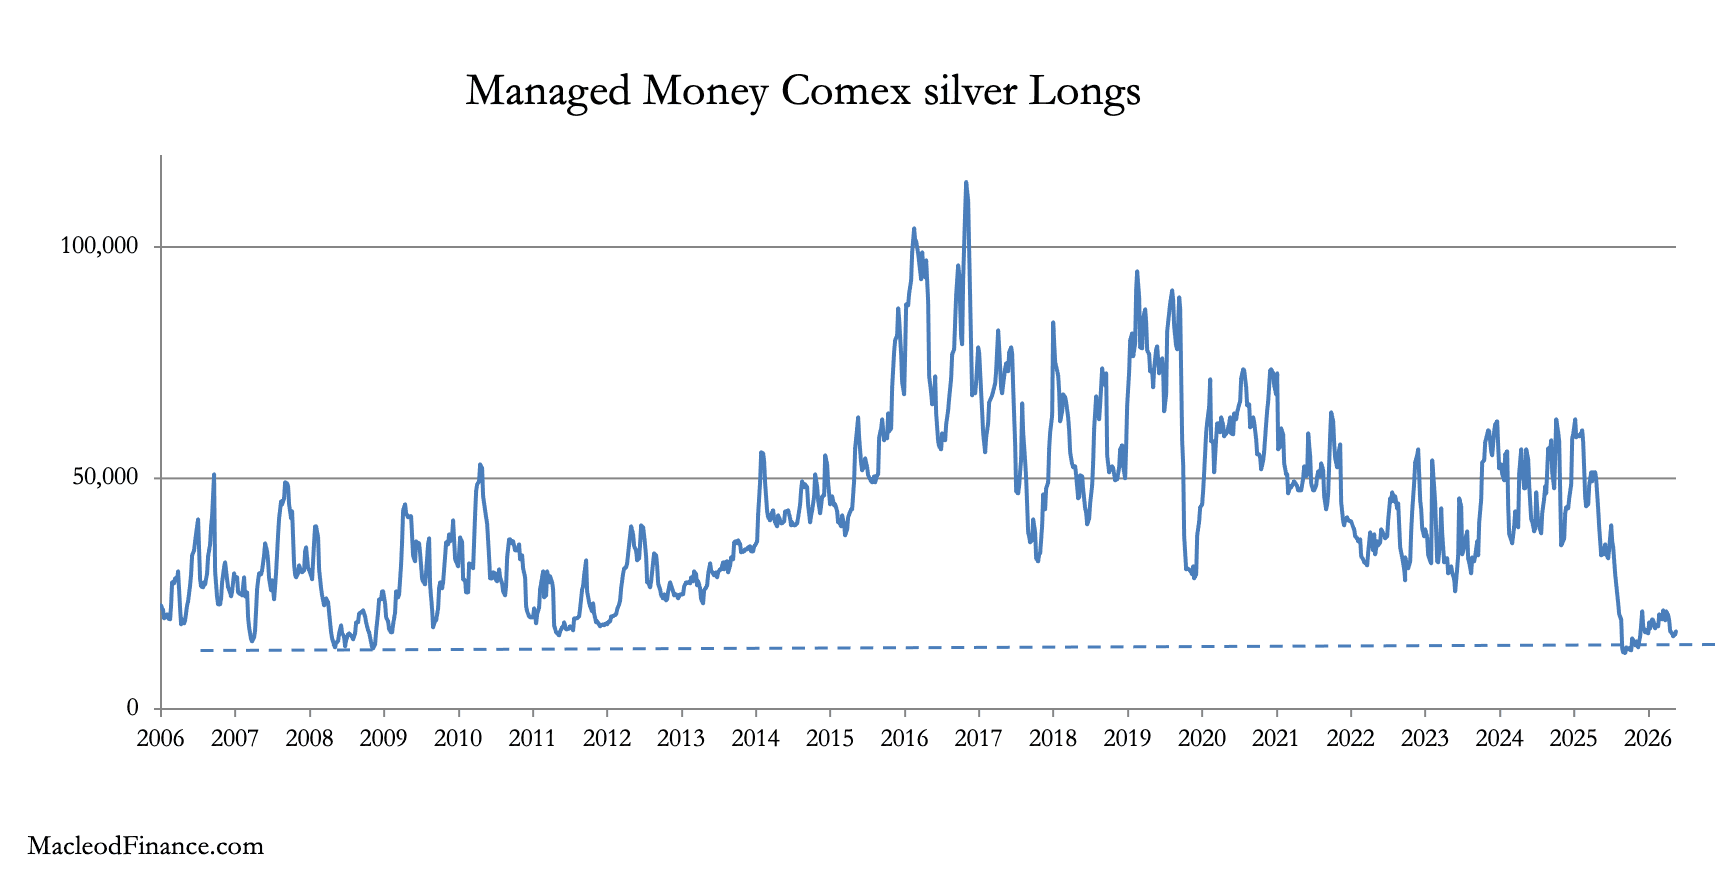
Finally, silver’s supply situation still appears tight ensuring continuing volatility relative to gold. Comex deliveries this year total 9,500 tonnes so far, and warehouse stocks have declined 3,575 tonnes. Meanwhile, speculator longs in the hedge funds are still at the lowest level for 20 years: